Protect the sale price before an offer comes in.
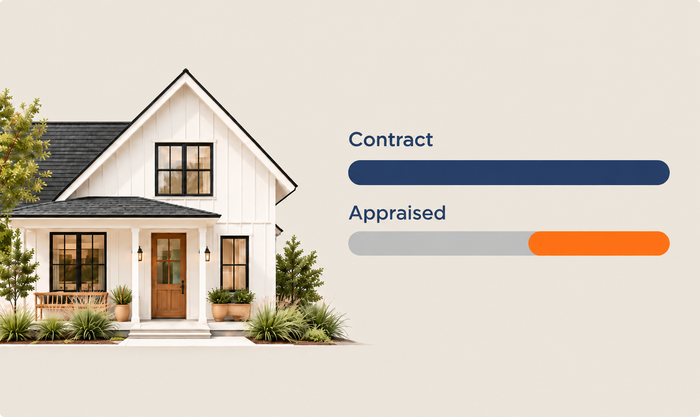
Embrace can certify a home's value before a buyer submits an offer. Later, if an eligible Embrace buyer's appraisal comes in below the certified value, Embrace makes will make up the difference.*
The buyer doesn't have to bring additional money for the appraisal gap, and the seller doesn't have to lower the agreed price.
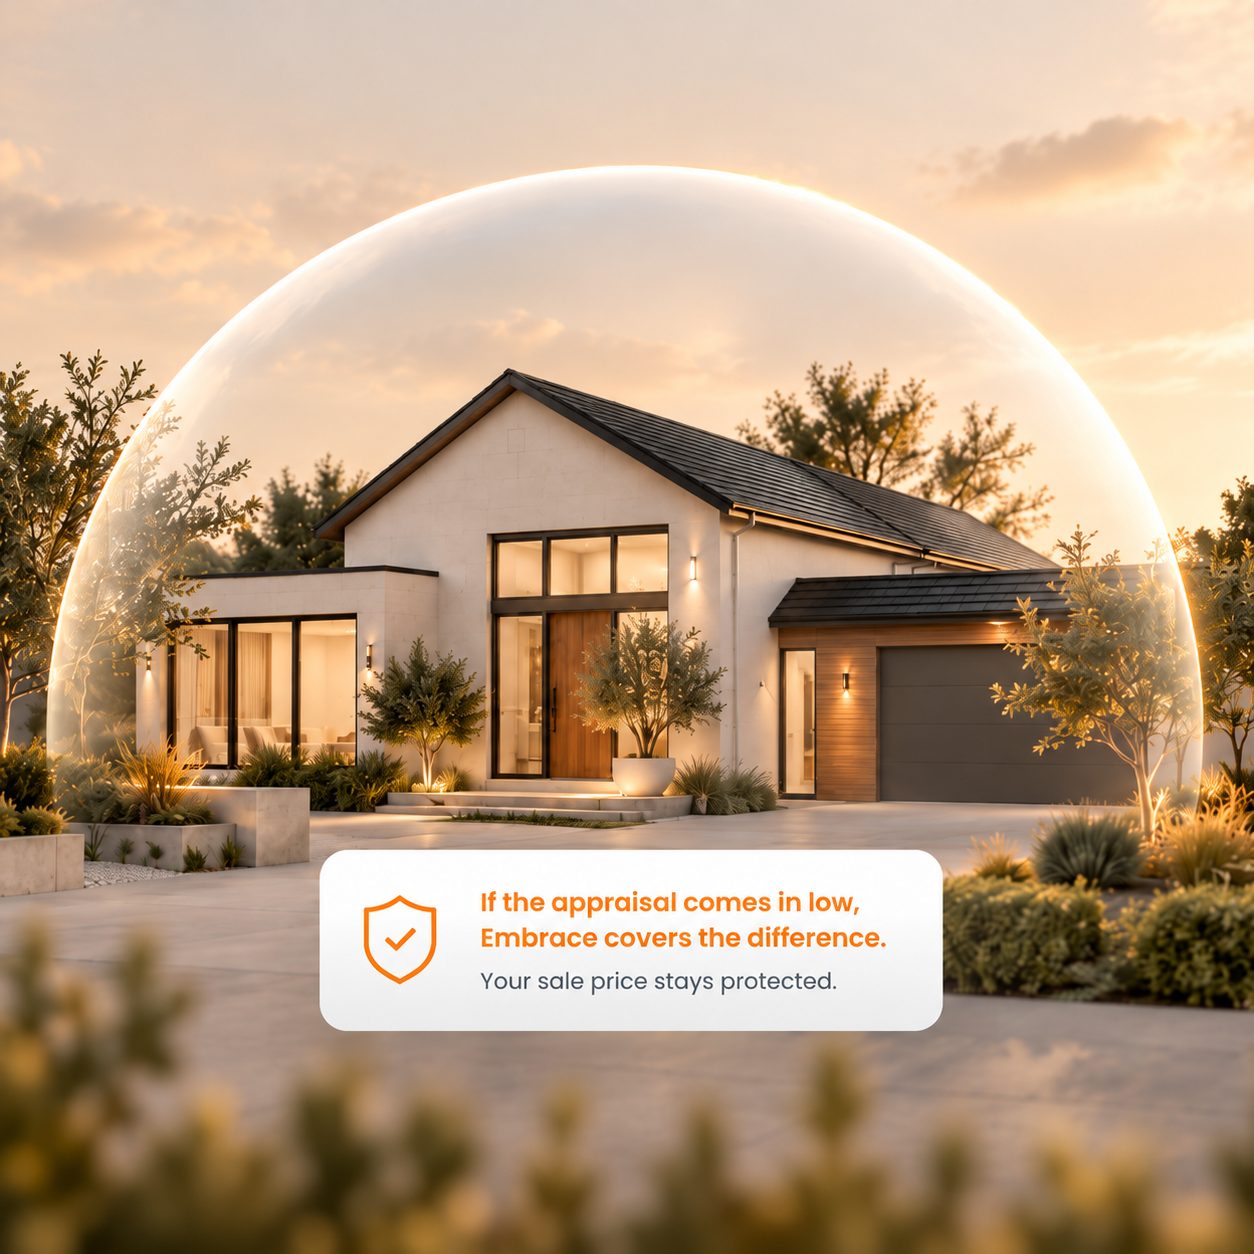
A low appraisal can change the deal.
Without appraisal-gap protection, the buyer may need to bring more money, the seller may be asked to lower the price, or the transaction may be put at risk.
A Property Value Certificate helps address that uncertainty before the offer is submitted.
Property value certified before the offer. Protection if the appraisal comes in low.
Submit the listing
Share the property address and expected list price. An Embrace loan officer reviews the property and confirms whether it qualifies for a PVC.
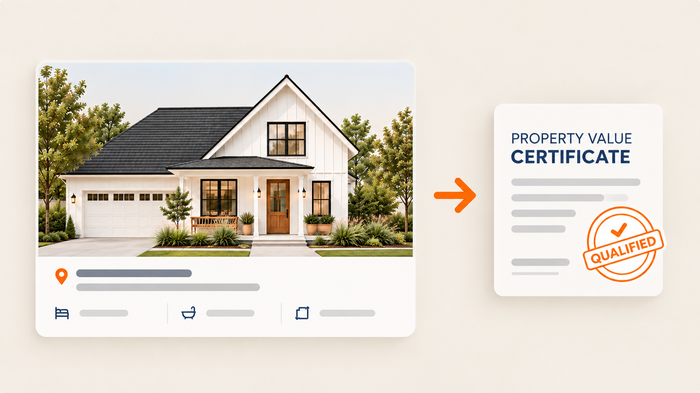
Connect an eligible buyer
If a buyer qualifies for Embrace financing, the certificate can be applied to that buyer’s transaction. The buyer may then choose to waive the appraisal contingency.
Cover an shortfall
If the final appraisal is below the certified value, Embrace covers the eligible shortfall up to the certificate’s stated limit, subject to program terms.
See if your listing qualifies.
Request a Property Value Certificate before the offers arrive.
Check a listingA stronger offer for the buyer. More certainty for the seller.
More confidence in the agreed price
- Address appraisal risk before offers arrive
- Give buyers another reason to consider the property
- Reduce the likelihood that a low appraisal leads to a price renegotiation
- Show sellers that you bring useful tools to the listing
A stronger offer without personal appraisal-gap risk
- Choose to waive the appraisal contingency
- Avoid paying additional money if the appraisal comes in short
- Give the seller greater confidence in your offer
- Compete more effectively with cash offers
Turn the PVC into a listing advantage.
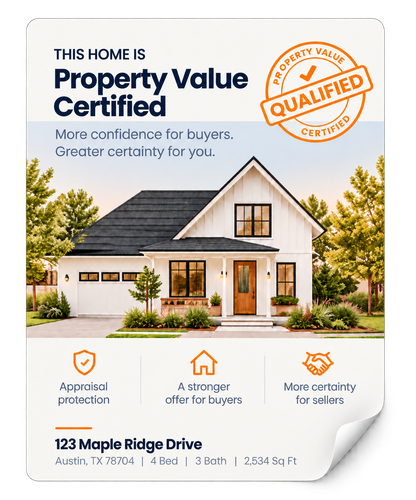
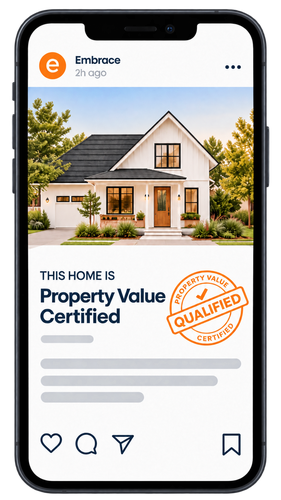
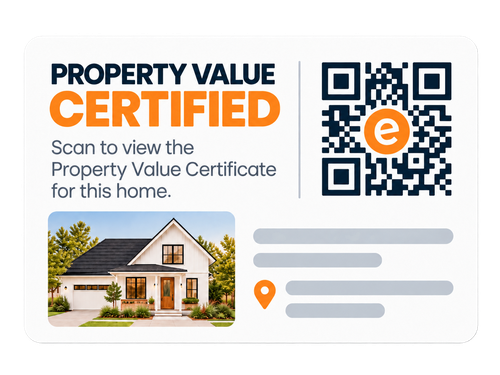
Once the property qualifies, use the Property Value Certificate across your listing marketing to show prospective buyers that the home comes with an added level of appraisal protection.
- Property Value Certified badge
- Listing flyer
- Social media graphics
- Open house signage
- QR code linking to the property's PVC page
- Buyer's agent email
Questions agents ask first.
Eligible properties include single-family homes, planned unit developments, and condominiums used as a primary residence or second home.
The buyer must be an active Embrace customer using an eligible conforming purchase loan, including HomeReady® or Home Possible®. The loan must have passing automated underwriting results and a maximum loan-to-value and combined loan-to-value ratio of 95%. Non-conforming and jumbo® loans are not eligible.
Yes. A listing agent can work with an Embrace loan officer to request a certificate before a buyer is attached. If an eligible Embrace borrower later wants to purchase the home, Embrace can convert the listing certificate to a borrower-specific certificate.
For an eligible transaction, Embrace can provide financing based on the certified home value even when the final appraisal is lower. This appraisal-gap protection may reduce the need for the buyer to bring additional money or ask the seller to renegotiate the price. Embrace may still order an appraisal or conduct a property review, and all standard loan and underwriting requirements continue to apply.
The request may move to a manual review. Embrace may approve a lower certified value when the original amount cannot be supported. If the property or transaction does not meet program requirements, the request may be declined.
An Embrace Property Value Certificate (PVC) establishes the home value Embrace may use when financing an eligible buyer’s purchase. Embrace determines the certified value using automated valuation models and available market data. The certificate is not an appraisal or a loan approval.
Contact an Embrace loan officer and provide the property address and expected listing price. The loan officer will submit the request and provide the certificate if the property qualifies. No buyer is required to begin the property review.
No. The buyer still finances the purchase through Embrace. The certificate does not guarantee the transaction, change the purchase contract, or automatically waive the appraisal contingency. The buyer decides whether to waive the contingency with guidance from their real estate agent and other advisors.
An executed purchase contract must be provided within 14 days of the certification date. In New York, the contract must be provided within 21 days. The certificate will show its applicable expiration date.
Check the home before the offers arrive.
See whether your listing can qualify for an Embrace Property Value Certificate.